What Is Payment Routing? How It Works and Why It Matters for High-Risk Businesses
- October 9, 2026
- Soham Guchait
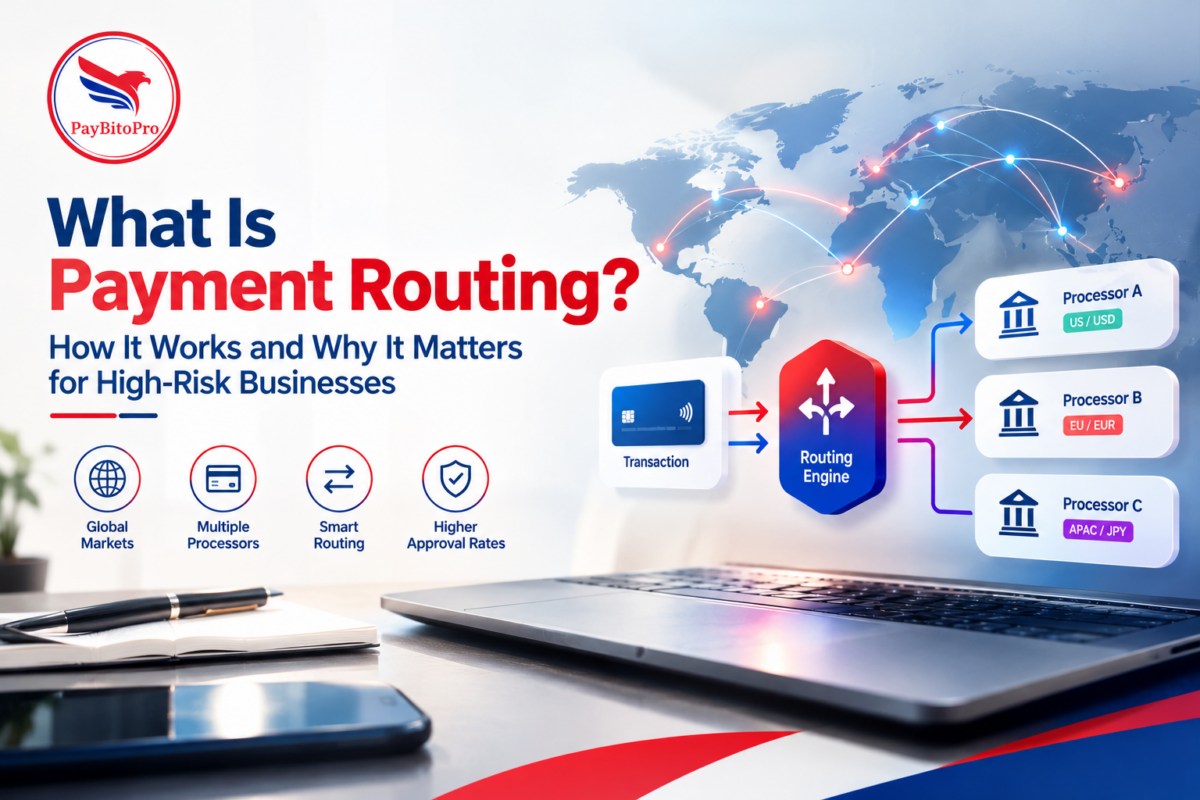
A customer clicks the Pay button. The bank has enough information to make a decision, but the transaction still needs to reach the right processing connection first. If the merchant sends every payment through the same provider, it may miss opportunities to use a better-suited route for a particular market, currency, or payment method.
That is where payment routing comes in.
Payment routing determines where a transaction goes for processing. For high-risk businesses, the decision can affect approval performance, processing costs, and the ability to keep accepting payments when a provider experiences problems. It also has limits: Choosing a different processor cannot force a bank to approve a transaction or remove restrictions from a merchant account.
What Is Payment Routing in Payment Processing?
Payment routing is the process of directing a transaction to a selected payment processor, acquirer, or processing connection based on predefined rules or decision logic.
A business using one processor may have little choice about where it sends transactions. A merchant connected to several approved providers, however, can decide which connection should handle a payment based on factors such as currency, card region, transaction type, provider availability, or processing costs.
Imagine an online business that accepts payments from customers in the United States and Europe. One provider may offer suitable coverage for US transactions, while another may support the merchant’s European payment methods more effectively. Routing rules can direct payments accordingly instead of treating every transaction as identical.
The aim is not simply to send payments through the cheapest provider. A suitable route must also support the transaction, comply with the merchant’s processing agreement, and offer acceptable performance.
How Does Payment Routing Work?
Routing happens as part of the payment flow, usually after the customer submits the transaction and the payment system has collected the information needed to make a routing decision.
A typical process follows these steps:
- The customer submits a payment – The checkout collects the required payment details and sends the transaction request securely.
- The routing system evaluates the transaction – It checks the applicable rules, which might include currency, card region, payment method, provider availability, or transaction limits.
- The system selects a processing connection – It sends the transaction to an eligible processor or acquiring connection.
- The payment provider processes the request – The transaction moves through the relevant payment infrastructure to the issuing bank, which makes the authorization decision for a card payment.
- The response returns to the merchant – The payment system records the outcome so the business can monitor performance and investigate failures.
One important distinction: The routing system selects the processing path, but it does not make the issuer’s approval decision. A well-chosen route can improve how a merchant handles transactions, yet the bank may still decline a legitimate payment.
Which Routing Strategies Can Merchants Use?
The right routing method depends on the merchant’s provider setup, transaction volume, and business requirements. Three common approaches illustrate how routing decisions can work.
Rule-Based Routing
Rule-based routing uses conditions set by the merchant or payment platform. For example, a business might send transactions in a particular currency to a provider that supports that market, or direct certain payment methods to a compatible connection.
These rules are relatively easy to understand and audit. However, merchants need to review them regularly. A rule that worked well six months ago may no longer make sense after a provider changes its pricing, supported markets, or processing limits.
Performance-Based Routing
Performance-based routing uses measured results to help select a provider. A merchant might compare approval rates, technical error rates, response times, and processing costs across eligible connections.
But there is a catch. A provider with a higher approval rate for one type of transaction may perform worse for another. Merchants should compare similar transactions rather than routing everything toward whichever provider has the highest overall approval figure.
Availability-Based Routing
Availability-based routing directs transactions away from a processing connection when it becomes unavailable or encounters a technical problem, provided another eligible connection exists.
This can help reduce disruption during provider outages. The system still needs to distinguish a confirmed failure from an uncertain transaction outcome. If the first provider may already have processed a payment, sending the same transaction elsewhere without checking its status can create duplicate-payment risks.
Why Payment Routing Matters for High-Risk Businesses
High-risk merchants may face stricter underwriting requirements, higher processing fees, additional monitoring, and fewer providers willing to support their business model. A carefully managed routing setup can help them use their approved processing connections more effectively.
Consider a subscription merchant that processes recurring payments across several markets. One provider may handle certain transactions well but experience technical issues with a specific payment method. If another approved connection supports that method, a routing rule may help the merchant direct eligible transactions to the alternative.
This is one part of payment processing optimization for high-risk merchants, where routing works alongside accurate transaction data, checkout improvements, provider management, and fraud controls.
Routing can also support business continuity, but it does not replace a genuine backup arrangement. Merchants using multiple providers need to confirm that each provider has approved their business and can process the relevant transaction types. They must also understand the costs, settlement terms, and restrictions attached to each account.
Payment Routing vs. Payment Cascading
These terms are related, but they describe different decisions.
Payment routing selects the processing connection for a transaction before the system submits it. Payment cascading comes into play when an initial attempt fails and the system considers sending an eligible transaction through another connection.
For example, a routing rule may direct a transaction to Processor A because it supports the customer’s payment method. If a technical error prevents that attempt from completing, cascading may allow another attempt through Processor B, provided the original outcome and applicable rules permit it.
A decline does not automatically justify another attempt. Merchants need to consider the failure reason, duplicate-payment risk, and provider requirements. Payment cascading and the recovery of failed transactions explores this distinction in more detail.
When Should a Merchant Consider Payment Orchestration?
Managing several processors through separate integrations can become difficult as a business expands. Teams may need to maintain different technical connections, monitor performance across providers, reconcile settlements, and update routing rules.
Payment orchestration can bring these activities into a common coordination layer. Depending on the platform, it may manage routing logic, connect multiple payment providers, centralize reporting, and support failover procedures.
It is not essential for every business. A merchant with one processor and a simple checkout may not gain enough value to justify the extra system. Businesses with several providers, markets, and payment methods may benefit from centralized management.
The distinction between the two technologies becomes clearer when examining how payment orchestration coordinates payment services. Merchants comparing technical architectures can also consider the differences between a payment gateway and payment orchestration.
How to Build a Better Payment Routing Strategy
Before introducing complex routing rules, merchants should establish a clear picture of their current performance.
- Compare similar transactions: Review approval rates, technical failures, costs, and response times by market, currency, payment method, and provider.
- Check provider restrictions: Confirm that each processing connection supports the merchant’s business model and the transactions it will receive.
- Define clear routing rules: Use business needs and measured results rather than assumptions about which provider performs best.
- Test alternative routes carefully: Monitor duplicate payments, fraud outcomes, processing costs, and approval performance after each change.
- Review the rules regularly: Update them when providers change their capabilities, commercial terms, or account restrictions.
Merchants should also understand how routing decisions interact with [strategies for improving payment approval rates in high-risk industries — link to: How to Improve Payment Approval Rates for High-Risk Businesses]. Routing can influence which provider receives a transaction, but checkout quality, issuer decisions, authentication, and fraud screening also affect the final outcome.
Conclusion
Payment routing helps merchants choose an appropriate processing connection for each transaction instead of sending every payment through the same path. For high-risk businesses, that flexibility can support better provider management, more informed processing decisions, and fewer disruptions when a connection becomes unavailable.
The strongest strategy starts with reliable transaction data, approved processing relationships, and clear routing rules. Add complexity only when the results justify it. A different route can improve the way a payment gets processed, but it cannot guarantee approval or replace sound risk management.
Categories
- ACH Payments (10)
- adult payment processing (11)
- AI (9)
- Altcoins (10)
- Banking (10)
- Bitcoin (133)
- Bitcoin ETF (11)
- Bitcoin Price (30)
- Blockchain (50)
- Brokering World Hunger Away (16)
- Business (17)
- card payment processing (10)
- CBD (11)
- CBDC (11)
- Chargeback (8)
- coaching business (11)
- COVID-19 (3)
- Crypto ATMs (1)
- Crypto Banking (17)
- Crypto Bill (1)
- Crypto business owner platform (31)
- Crypto Investment (3)
- Crypto Markets (5)
- Crypto Payment (35)
- Crypto Payment Processor (4)
- Crypto Prices (1)
- Crypto Trading (92)
- Cryptocurrency (402)
- Cryptocurrency Exchange (108)
- Data Visualization (2)
- dating platforms (11)
- debt collection payment processing (10)
- Decentralized Finance (7)
- DeFi Payment (9)
- DEX (3)
- Digital Currency (23)
- dropshipping payment processing (12)
- Ethereum (2)
- FAQ (7)
- file sharing payment processing (11)
- Finance (25)
- Financial Equality (4)
- Financial Freedom (8)
- Forex (35)
- hemp (1)
- ICO (2)
- Investment (11)
- IPTV (11)
- Merchant Account (10)
- Mining (3)
- News (66)
- NFTs (2)
- online gambling (11)
- P2P (1)
- Paybito (147)
- PayBitoPro (693)
- PayBitoPro Coin Listing (6)
- PayBitoPro Exchange (2)
- Payment Gateway (48)
- peptide (10)
- Post COVID Digital Transformation (1)
- Press Release (130)
- Privacy & Security (3)
- Real Estate (1)
- Stablecoin (5)
- Technology (15)
- Travel (11)
- Uncategorized (10)
- US Presidential Election (2)
- Utility Coin (1)
- Web3 business (4)
- Web3 Wallets (2)
- White Label Crypto Exchange (8)
Recent Posts
- Payment Gateway vs. Payment Orchestration: What’s the Difference?
- What Is Smart Payment Routing? Strategies to Optimize Payment Performance
- How to Improve Payment Approval Rates for High-Risk Businesses?
- Why Are Online Payments Failing? Common Causes and How to Fix Them
- How to Use Multiple Payment Processors to Reduce Business Disruptions?